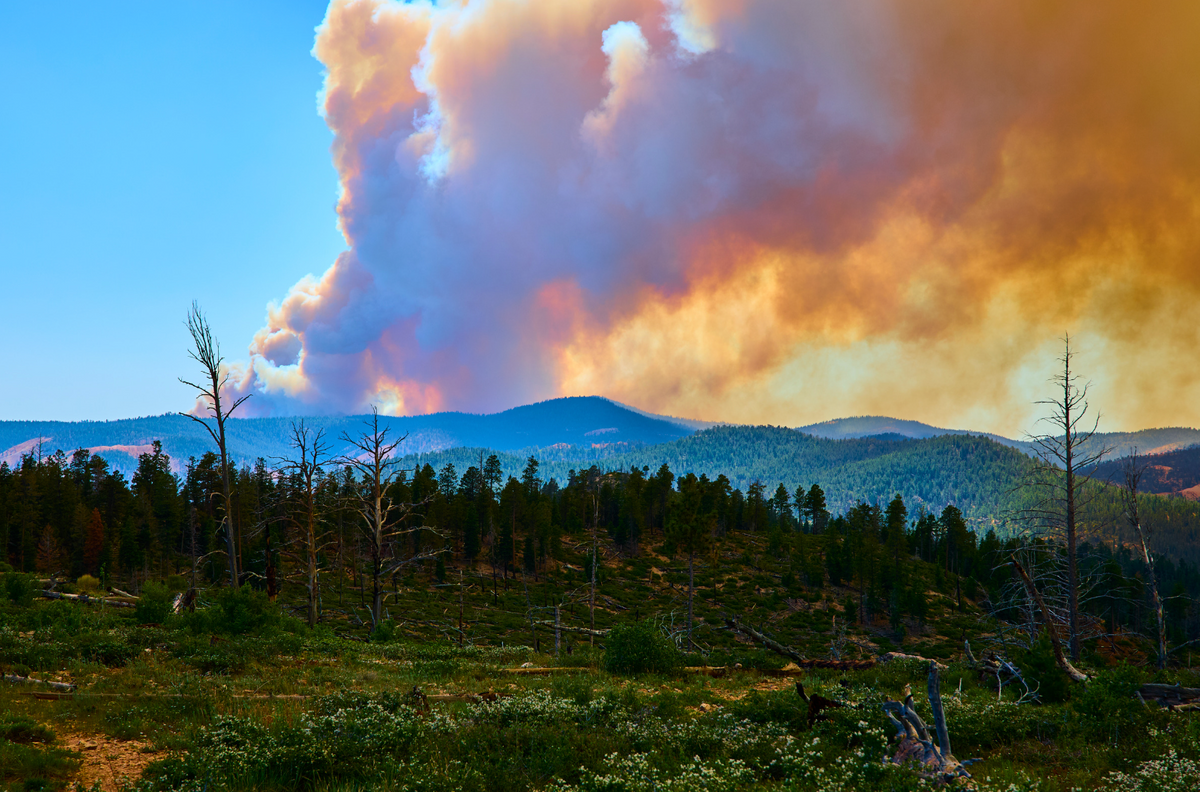
On the afternoon of August 19, 2026, a fire broke out near Avenue 42 and Road 38 outside Alpaugh in southwestern Tulare County. Within hours, the entire town was under an evacuation warning. By the next day, the Alpaugh Fire had burned about 3,600 acres, according to CAL FIRE. Evacuation warnings were lifted on August 20, but it was a clear reminder that wildfire risk isn't limited to the mountains.
Dry grass, farm fields, and brush can carry fire quickly across the Valley floor, while foothill communities from Three Rivers to Springville face their own risks every year. This wildfire preparedness checklist walks you through the three things that matter most: hardening your home, documenting what you own, and making sure your insurance will actually cover you if the worst happens.
Key Takeaways
Wildfire risk in the Central Valley includes grass and agricultural fires on the Valley floor, not just foothill and mountain fires.
Defensible space is organized into three zones: 0–5 feet, 5–30 feet, and 30–100 feet from your home.
A home inventory with photos and video, stored in the cloud, can speed up your claim after a loss.
Many homeowners are underinsured because their dwelling limit hasn't kept up with rebuilding costs.
Review your policy's dwelling, contents, and additional living expense limits before fire season peaks.
Part 1: Defensible Space Wildfire Preparedness Checklist
Defensible space is the buffer between your home and the grass, trees, and brush around it. It slows the spread of fire and gives firefighters a safer place to work. Ready for Wildfire, CAL FIRE's preparedness program, breaks it into three zones.
Zone 0: The Ember-Resistant Zone (0–5 Feet)
This is the most critical area, since embers landing next to your home cause many structure ignitions.
☐ Replace bark mulch near the house with gravel, pavers, or concrete
☐ Remove dead plants, leaves, and pine needles from the ground, roof, and gutters
☐ Move firewood, lumber, and propane tanks away from the house
☐ Relocate combustible patio furniture, doormats, and planters during red flag days
☐ Trim branches at least 10 feet from your chimney
California's Board of Forestry approved formal Zone 0 regulations in August 2026. They're expected to roll out over several years for existing homes in higher-risk areas, so check with your local fire agency on how they'll apply to your property.
Zone 1: Lean, Clean, and Green (5–30 Feet)
☐ Remove dead plants, grass, and weeds
☐ Keep trees spaced so branches are at least 10 feet apart
☐ Remove flammable plants from under windows and decks
☐ Keep lawns watered and mowed
Zone 2: Reduce Fuel (30–100 Feet)
☐ Cut annual grass to a maximum height of 4 inches
☐ Create horizontal and vertical space between shrubs and trees
☐ Keep fallen leaves and debris no deeper than 3 inches
☐ Clear dry weeds along fence lines and field edges
Home Hardening Upgrades
☐ Install ember-resistant vents with fine metal mesh
☐ Upgrade to a Class A fire-rated roof when it's time to replace
☐ Use dual-pane, tempered glass windows
☐ Enclose eaves and cover gaps where embers can enter
Some of these upgrades may also qualify you for insurance discounts, so let your agent know when you complete them.
Part 2: Document Your Home Before Fire Season
After a wildfire, the last thing you want is to try to list everything you owned from memory. A home inventory makes the claims process faster and helps you recover the full value of your belongings.
☐ Walk through every room with your phone and record video, narrating what you see. Open closets, drawers, and cabinets.
☐ Photograph high-value items like electronics, jewelry, tools, and collectibles, including serial numbers.
☐ Don't forget the garage, shed, and yard. Tools, bikes, and outdoor equipment add up quickly.
☐ Save receipts for major purchases and home improvements.
☐ Store everything in the cloud or with a trusted relative outside your area, not just on a laptop at home.
☐ Update your inventory once a year, ideally before summer.
California law has made the post-fire claims process a bit easier. Starting in 2026, after a declared disaster, insurers can pay up to 60% of your contents coverage limit (capped at $350,000) without requiring an itemized inventory for a total loss. That's helpful, but a thorough inventory is still the best way to recover the full amount you're owed.
Part 3: How Home Insurance Coverage Gaps Show Up After a Wildfire
Home insurance for wildfire in California generally covers fire damage under a standard homeowners policy or a California FAIR Plan policy. But many families discover gaps only after a loss. Here are the most common ones.
Underinsured Dwelling Coverage
Your dwelling limit should reflect what it would cost to rebuild your home today, not its market value or what you paid for it. Construction and labor costs have risen significantly in recent years, and a limit set five or ten years ago may fall short. Ask whether your policy includes extended replacement cost, which pays a percentage above your limit if rebuilding costs spike after a disaster.
Contents Coverage That's Too Low
Personal property coverage is often set as a percentage of your dwelling limit. If you own a lot of tools, equipment, or valuables, it may not be enough.
Additional Living Expenses (ALE)
If you can't live in your home, ALE helps pay for temporary housing, meals, and other extra costs. After a major wildfire, rentals can be scarce and expensive, so make sure your ALE limit is realistic.
Code Upgrade Coverage
Rebuilding often requires meeting current building codes, which can add to the cost. Building code upgrade coverage (sometimes called ordinance or law coverage) helps pay the difference.
FAIR Plan-Only Coverage
If you're on the California FAIR Plan, remember it's fire-focused and doesn't include liability or theft. A Difference in Conditions (DIC) policy can help fill those gaps.
Your Evacuation Go-Bag Checklist
☐ Medications, glasses, and first aid supplies
☐ Copies of IDs, insurance policies, and important documents
☐ Phone chargers and a battery pack
☐ Water, snacks, and a change of clothes
☐ Pet food, leashes, and carriers
☐ Your agent's phone number and your policy number
Let's Review Your Coverage Before the Next Fire
Preparation is the best protection. At Abraham Guillen Insurance in Visalia, we've helped Central Valley families review their coverage for more than 28 years. Learn more about our natural disaster insurance and homeowners insurance options, or call (559) 839-2020 to schedule a policy review.
FAQ
Does homeowners insurance cover wildfire damage in California?
Yes, standard homeowners policies and California FAIR Plan policies cover fire damage, including wildfire. The key is making sure your limits are high enough to rebuild and replace your belongings.
Can my insurer cancel my policy after a nearby wildfire?
After a declared wildfire emergency, California's Insurance Commissioner can order a one-year moratorium on non-renewals for homes in or next to the affected area. Contact the California Department of Insurance or your agent for details.
When is wildfire season in the Central Valley?
Fire activity typically peaks from summer into fall, but dry conditions can extend the season. It's smart to prepare year-round.
Does defensible space lower my insurance premium?
It can. Some insurers and the FAIR Plan offer discounts for wildfire mitigation such as defensible space, fire-resistant roofing, and ember-resistant vents.